
Global Oil Supply Faces Historic Threat: 14M BPD Disruption Continues
In a stark assessment, the International Energy Agency (IEA) has branded the Middle East conflict around the Strait of Hormuz the “largest supply disruption in the history of the global oil market.” The numbers justify the alarm. Since military tensions flared in late February 2026, the interruption of nearly 20 million barrels per day (mb/d) of oil transit—a fifth of global supply—has carved an average of 14 mb/d from the market. This historic shockwave sent Brent crude surging past $100 per barrel multiple times since March, with a peak of $126. The consensus among analysts is clear: the market is now entering a “more dangerous phase.”
Strait of Hormuz: A Critical Chokepoint Under Siege
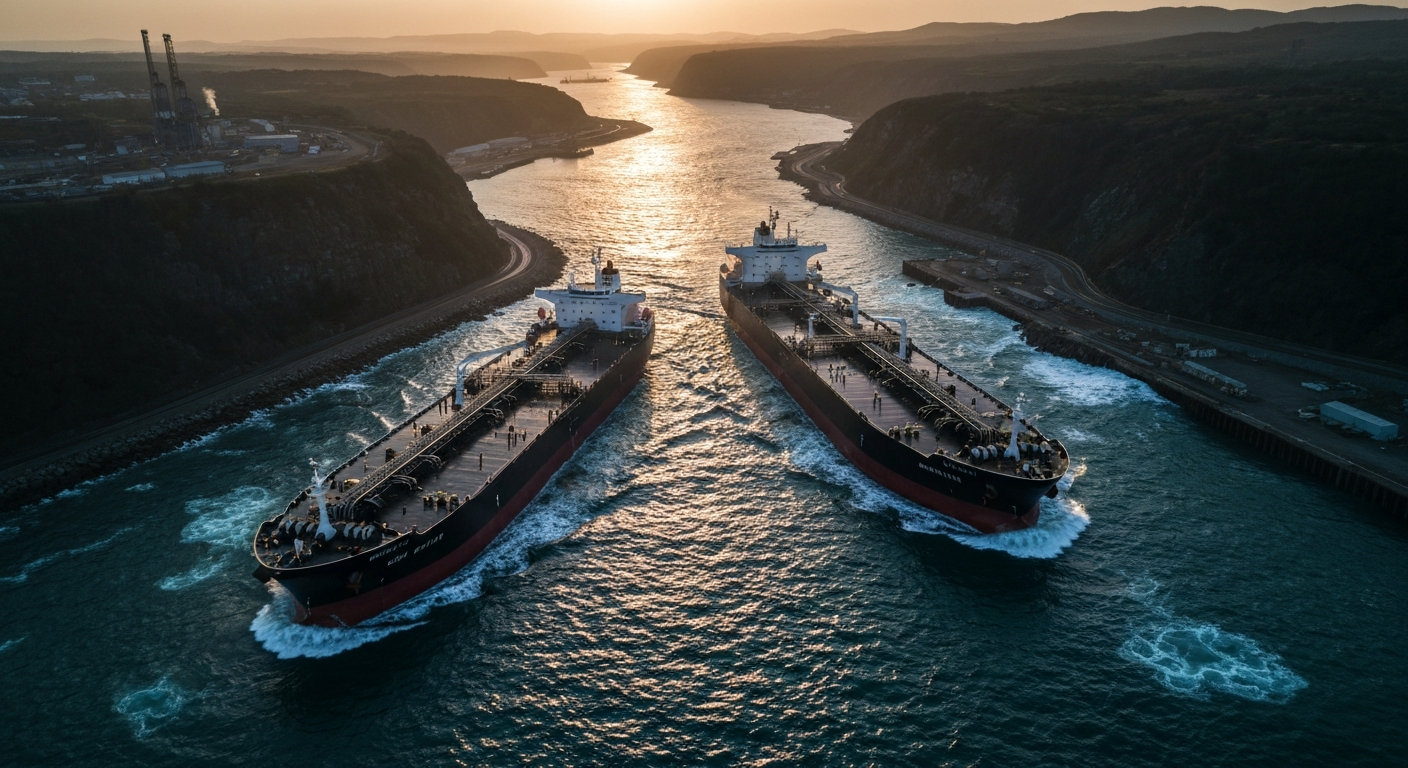
No maritime chokepoint is more vital to the global oil trade than the Strait of Hormuz, the narrow passage between Oman and Iran. Through this artery flows 20% to 25% of the world’s seaborne oil—an average of 20.9 mb/d in the first half of 2025 alone. Renewed military tensions have now clamped down on this critical flow. With Iran reportedly closing the waterway to allied vessels and turning back others, daily transits have plummeted, at times grinding to a near halt. The fallout extends far beyond crude, disrupting huge volumes of liquefied natural gas (LNG) and other commodities, which in turn spikes global trade costs and fuels inflationary pressure.
These tensions have forced a dramatic re-evaluation of the oil market’s stability. Diplomatic overtures may have recently pulled Brent crude back to the high $80s, but prices remain dangerously elevated from pre-conflict levels. More importantly, the IEA flags a critical shift in the nature of the crisis. The focus is no longer just on crude oil availability; the real choke point is now the tightening supply of refined fuels like diesel and gasoline, as refineries worldwide struggle to meet demand.
Strategic Responses and Eroding Buffers
To mitigate the crisis, nations have deployed their ultimate weapon: strategic reserves. IEA member countries orchestrated their largest-ever coordinated release on March 11, pledging 400 million barrels to the market, of which 290 million have already been deployed. The cost of this intervention is starkly visible in the United States’ Strategic Petroleum Reserve, now drained to around 310 million barrels—its lowest point since 1983. This massive drawdown has left global buffers “largely depleted,” stripping the market of its safety net against future shocks.
Beyond stock releases, producers have scrambled for workarounds. Saudi Arabia and the United Arab Emirates are redirecting crude through alternative pipelines, leveraging an estimated 3.5 to 5.5 mb/d of capacity to bypass the Strait of Hormuz. At the same time, a surge in production from non-OPEC+ nations—notably the United States, Brazil, Venezuela, and Kazakhstan—is helping to fill the gap left by lost Gulf supplies. On the demand side, a surprising brake on prices has come from China, whose crude oil imports have plummeted by nearly half, easing pressure on the global balance.
OPEC+, for its part, is sticking to its script. The cartel plans to hike output targets by another 188,000 barrels per day for September, officially completing the rollback of its 2023 voluntary cuts. The problem? These are paper barrels. Actual production from the group languishes far below its quotas due to the very conflict disrupting the market. This growing chasm between stated policy and physical capacity injects yet another layer of uncertainty into an already fragile situation.
Navigating a Volatile Energy Landscape
The IEA’s warning against “complacency” could not be more timely. Geopolitical conflict has permanently transformed critical supply routes into high-risk zones, and temporary fixes like stockpile releases cannot defy the gravity of a fundamental supply crisis. For investors and policymakers, navigating this landscape requires an intense focus on three indicators. First, any geopolitical shift in the Middle East will directly impact the frequency and severity of disruptions. Second, global inventories, especially for refined products, are the most direct gauge of market tightness. Finally, the gap between OPEC+ production quotas and actual output reveals the true state of global spare capacity. In an energy market now defined by persistent volatility, vigilance is the only viable strategy.
References &
